Most cost surprises at the dentist happen because nobody wrote anything down. A figure mentioned in the chair, a nod, and then an account at the end that looks nothing like what you remember. Informed financial consent exists to stop that: before you agree to treatment, you should know roughly what it will cost, what could push that figure up, and how to check what your health fund will pay.
It does not mean a fixed, guaranteed price for every procedure. Teeth do not always behave the way an X-ray suggests, and the Australian Dental Association's own policy accepts that a dentist may only be able to give a range. A good written estimate is clear about that uncertainty instead of hiding it.
Talking about cost is part of consent
Clinical consent means you understand what is being proposed for your teeth, the alternatives and the risks. Financial consent is its companion. The Australian Dental Association's Policy Statement 5.16 describes informed financial consent as part of sound ethical professional practice, which puts it in the same category as explaining the treatment itself rather than treating it as front desk administration.
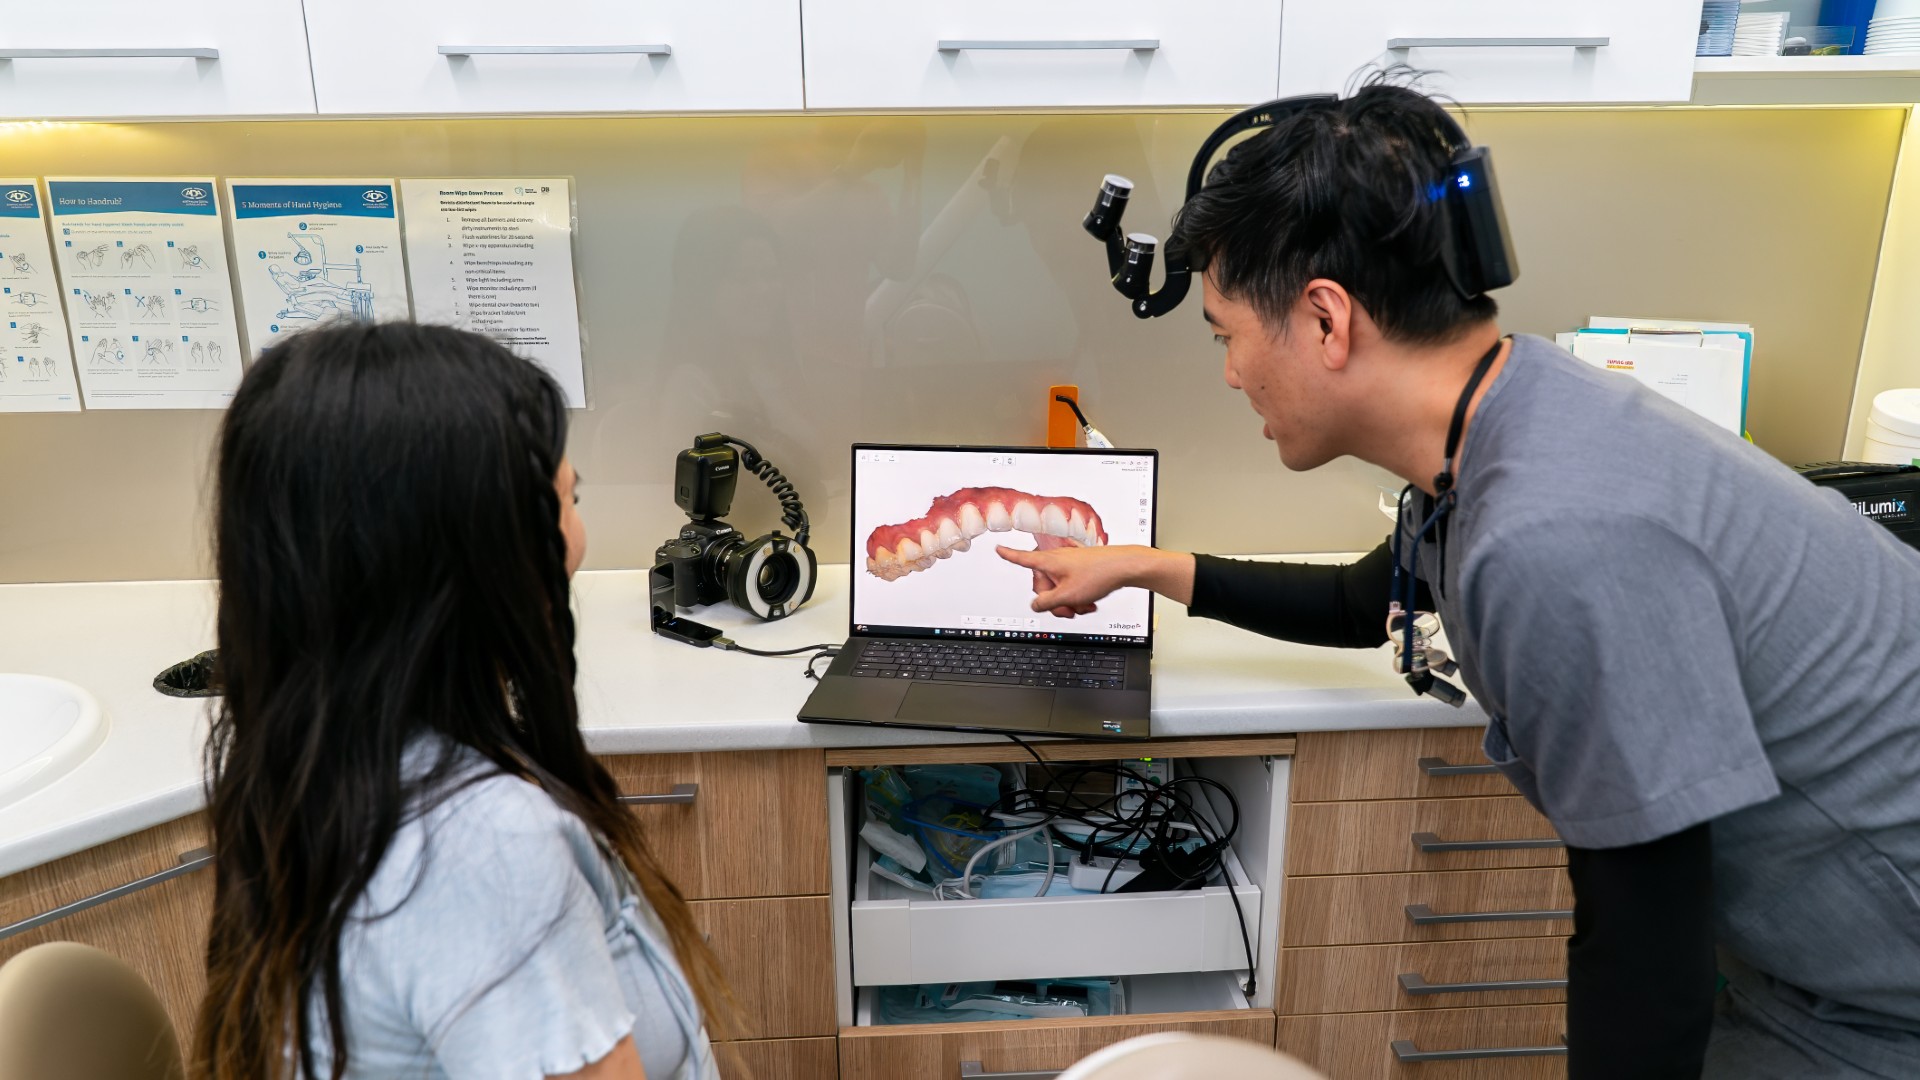
The same policy says the dentist should take reasonable steps to check that you have understood the estimated cost. A printed sheet handed over on the way out does not achieve that by itself. A useful test: could you explain the figure, and what might change it, to someone at home?
The policy also allows for emergencies. When someone arrives in severe pain or with an injury, waiting for a detailed financial discussion could delay care that cannot wait, so the full conversation may sensibly come after the urgent problem is dealt with.
A range is often the accurate answer
Dental fees are set either per item of treatment or by the time a procedure takes. Policy Statement 5.16 recognises this and notes that estimates will often be a range of fees. It also says an estimate given before treatment should state that it is not guaranteed, and that the cost may rise if the procedure takes longer than expected or if other procedures turn out to be needed.
A familiar example is an old filling. On the X-ray it may look sound, but once the old material is removed there can be decay underneath that changes what the tooth needs. If that possibility is raised before treatment, a higher final account makes sense. If it is not, the same account feels like a surprise.
For bigger courses of treatment, such as crowns or dental implants, the plan is often staged. Each stage has its own estimate and a natural point to stop, review and decide on the next step, which is far easier to manage than one large figure agreed in a single conversation.
What to look for on a written estimate
The total is the least informative part of the document. These are the details that let you check it and plan around it:
- Each procedure with its item number. This is what your fund uses to assess a claim.
- A plain statement that the figure is an estimate. If the document says nothing about this, ask whether the figure is fixed.
- What could change it. Extra procedures, longer appointments or findings once work begins.
- Follow-up and maintenance. Reviews, cleaning, night guards or eventual replacement for work that is meant to last many years.
- How long the estimate stands. Laboratory and material costs move, so an undated estimate can cause confusion months later.
Policy Statement 5.16 also describes a written quotation, with the patient's acceptance recorded before treatment, as sound business practice that leads to fewer account disputes. That is the profession's description of good practice rather than a legal rule attached to every visit, but it is a reasonable thing for any patient to ask for. Our article on reading a dental treatment plan walks through the rest of the document.
Item numbers are how you check your rebate
Health funds do not assess descriptions such as "large filling on a back tooth". They assess the item number from the Australian schedule of dental services. The ADA policy says that where fees are itemised, patients should be given the relevant item numbers so they can confirm their health fund benefit or government rebate. Asking for them is routine and expected.
With the numbers in hand you can phone or log in to your fund and get a real answer about your benefit for each item. Without them, the fund can only speak in general terms, and you are left guessing at your out of pocket cost.
Only your health fund can confirm what it will pay
The ADA policy is direct on this point: patients are responsible for contacting their own private health insurer to confirm their cover and benefits. It also notes that policies vary so much that the rebate for the same service can differ widely from one person to the next.
That is not the practice stepping away from the conversation. Your fund holds information the practice cannot see, such as your level of cover, how much of your annual limit is left and whether a waiting period still applies. A practice can give you its fee and the item numbers. Any rebate figure it mentions should be treated as a guide until your fund confirms it.

At Lumi, health fund claims are made on the spot through HICAPS, so you see the benefit actually paid and your gap at the end of the visit. If the remaining amount for a larger plan is more than you expected, our guide to spreading the cost of dental treatment explains the usual options.
Three separate sources of rules
People often blend these together, but they carry different weight.
The ADA policy
Policy Statement 5.16 is the Australian Dental Association's own policy for the profession. It is the most detailed description of what good financial consent looks like, and the source of most of the points above. It is an association policy, not legislation.
The shared Code of conduct
Registered dental practitioners are bound by the shared Code of conduct adopted by the Dental Board of Australia and administered with Ahpra. Among other things, it expects practitioners to make sure patients are aware of fees and charges, preferably before treatment is provided. Concerns about a practitioner's conduct can be raised through Ahpra, and in New South Wales through the Health Care Complaints Commission.
Australian Consumer Law
General consumer law applies to dental practices as businesses. Statements about price must not be misleading. In everyday use a quote is a firm price for defined work and an estimate is indicative, but dental regulation does not define the two words separately, so the wording on your document matters more than the label.
Long-term upkeep is part of the cost
An estimate that covers only the appointment date can understate what a treatment costs over its life. The ADA policy includes information about the ongoing maintenance of treatment as part of informed financial consent, and this is the item most often left out.
Crowns, implants, dentures and orthodontic retainers all need reviews, professional cleaning and, eventually, repair or replacement. That is normal upkeep, not a failure. Knowing about it before you decide can change which option suits you, in the same way that delaying treatment tends to bring its own costs, as covered in what putting off dental care can lead to.
When the final account is well above the estimate
Start by asking for an itemised account and laying it beside the estimate. Usually the difference comes down to one or two added items, and the useful questions are which items were added, why they became necessary, and whether that possibility was mentioned beforehand. Asking for the explanation in writing gives you something to refer back to.
Most of these conversations are settled with the practice directly. If you remain unsure about further treatment, a second opinion before booking the next stage is reasonable. Concerns about conduct can go to Ahpra or the Health Care Complaints Commission, and for a large disputed sum or a signed finance agreement, a solicitor or a free financial counsellor is the right person to speak to.
Common questions
Must a dentist give me a written quote?
The ADA describes a written quotation with recorded acceptance as sound business practice, and the shared Code of conduct expects fees to be discussed, preferably before treatment. Neither turns a written quote into a legal requirement for every single appointment, but asking for one before anything beyond a routine visit is entirely reasonable.
Can the final fee be higher than my estimate?
Yes, if the treatment needed turns out to be different from what was planned. That is why the ADA policy says estimates should state they are not guaranteed. Where possible, a change should be explained to you before the extra work is done, not afterwards.
Is a verbal figure enough?
For a single routine item, a conversation often covers it. For anything larger, a verbal figure is hard for either side to check later, which is why the profession's policy favours writing it down.
Does a written estimate tell me my gap?
Not on its own. It gives you the fee and the item numbers. Your gap is the fee minus whatever your fund pays for those items, and only your fund can confirm that amount.
Ask for the details before you agree
You should never feel rushed into treatment without knowing what it is likely to cost. After an examination at Lumi Dental in Melrose Park you will usually receive a written treatment plan, often by email, and you are welcome to ask for the item numbers so you can check your benefit with your fund first. If you are new to the practice, see our current offers, or contact us to ask about the treatment you are considering.
This article is general information only. It is not legal or financial advice, and it is not a substitute for advice about your own circumstances, your own policy or your own teeth. Policies, professional guidance and benefits change and vary, so confirm cover with your own health fund. For a concern about a registered practitioner, contact AHPRA, or in New South Wales the Health Care Complaints Commission. For a disputed account or a signed agreement, speak to a solicitor or a financial counsellor.